

On the Amsterdam Stock Exchange this year, few stocks have seen such a wide divergence as ASML and Adyen. ASML is up nearly 60 percent since January 1. Adyen is down more than 30 percent, making it the biggest loser on the AEX. The difference between the two is about 90 percentage points. Yet we currently see an opportunity emerging for both. ASML is posting record results but is temporarily pulling back due to turmoil in the chip sector. Adyen itself continues to grow, but the stock’s valuation has had a tough year. The share price now appears to be finally bottoming out. In this article, we’ll walk you through ASML’s financials and show you exactly where Adyen stands.
On October 1, we published the article “ASML: Strong Recovery Ahead of Earnings. Price Target €2,350” on . We recommend reading this article first. You can find it HERE.
ASML: Record Quarter and Higher Full-Year Forecast
The third-quarter results are strong. Revenue rose by 55 percent to €11.7 billion. Net income came in at €5.0 billion, and the gross margin at 57.5 percent. Both are record highs. For the fourth quarter, ASML expects revenue to range between €14.2 and €15.2 billion. The full-year 2026 forecast has been raised for the third time this year, to €44 to €45 billion. That represents approximately 36 percent growth compared to 2025.
The most important signal is found in the notes to the financial statements. Customers are already placing orders for machines for 2029 and 2030. According to CEO Christophe Fouquet, the planned production for 2027 and 2028 will not be enough to meet all demand. ASML therefore does not have a demand problem, but a capacity problem.
So why is the stock price falling anyway?
The market reacted negatively. After a brief recovery on the day the results were released, ASML’s stock price fell to €1,422 today. On a weekly basis, the stock is down more than 9 percent. Since its record high at the end of June, it has lost about 18 percent. The causes lie largely outside ASML’s control. U.S. inflation came in higher than expected, leading investors to anticipate higher interest rates. In addition, doubts are growing about whether AI companies can sustain their massive investments. Earlier this week, a Chinese breakthrough in memory chips already put pressure on the entire sector. The stock is trading at nearly 55 times expected earnings. At such a valuation, there is little room for doubt.
The capacity shortage is also a factor. If ASML cannot deliver faster, it will take longer for the high demand to translate into revenue. The political situation also remains a risk. China accounts for about 20 percent of revenue, and Washington wants to further restrict exports of older DUV machines.
What do analysts think of ASML?
Most banks remain positive, and some have even become slightly more optimistic following the earnings report. UBS raised its price target to €2,400, Barclays to €2,500, and Citi to €2,300. Jefferies, on the other hand, lowered its target to €1,590. In our previous article, the average price target was around €2,000, approximately 25 percent above the price at that time. Due to the price decline, the current price is nearly 40 percent below that level.
What is Yelza’s outlook on ASML?
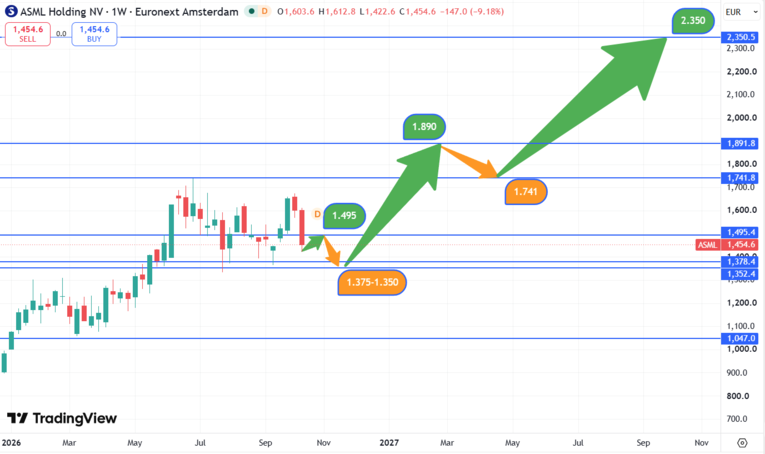
In our previous article, our model projected a rise to €1,890, with €1,480 as a key support level. That rise did not materialize. The correction has been deeper than expected, and the share price fell below €1,480. The scenario has thus shifted, but the price target remains unchanged.
Source: TradingView, analysis by Yelza
In the short term, our model expects a slight recovery to €1,495. That is the level of the broken support, which now acts as resistance. This is expected to be followed by a final correction to the zone between €1,375 and €1,350.
From that zone, our system expects a strong rally to €1,890. This may be followed by a brief pullback to €1,741, the record high set in June. After a breakout, a previous high often acts as a new low. From that level, the path is clear toward the unchanged price target of €2,350, to be reached in the course of 2027. That is well over 60 percent above the current price.
Adyen: From a Price Plunge to Bottom Formation
Adyen had a difficult year on the stock market. In February, volume figures for the second half of 2025 fell short of expectations, and the stock plummeted. In June, another blow of nearly 9 percent followed after a negative report from Cleveland Research regarding increasing competition. From its peak of over €1,600 at the end of 2025, the stock price more than halved to €772.
The half-year results released on August 13 painted a different picture. Net revenue rose by 19 percent to €1.3 billion. Processed payment volume grew by 24 percent to €804 billion. Adyen raised its growth forecast for 2026 to 21 to 23 percent, excluding currency effects. The stock rose by more than 16 percent that day, climbing above €1,000.
Most of those gains have since been given back. In early October, the share price fell back to around €855. This was followed by a recovery to over €925. This difference compared to earlier this year is significant. The new low is clearly above the previous low of €772. A higher low following a prolonged decline is often an early sign that selling pressure is easing.
There are also some points of concern. Adyen is earning slightly less per euro processed than it did a year ago, as major clients are receiving volume discounts for the first time. In addition, CFO Ethan Tandowsky left the company at the end of August. The quarterly update on October 28 will primarily need to show whether the strong growth in payment volume is continuing. If that growth holds up, investor doubts will continue to fade.
What do analysts think of Adyen?
Analysts are remarkably positive. The average price target from approximately 35 analysts is around €1,378, nearly 50 percent above the current share price. Price targets range from €887 to €1,900. It is striking that not a single analyst has a “sell” rating on Adyen, even though the stock is the worst-performing on the AEX. This suggests that analysts view the price decline primarily as an overreaction by the market, rather than a sign that the company is weakening.
What is Yelza’s view on Adyen?
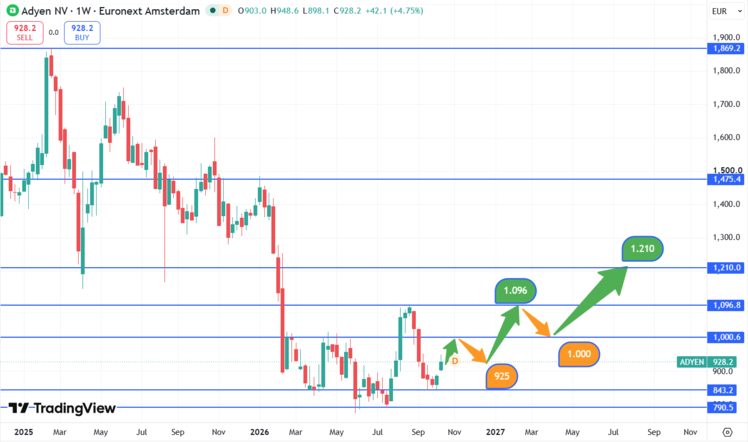
The chart below shows Adyen’s stock price performance since early 2025. It indicates that the stock has gone through a difficult period. The arrows represent the price trajectory we consider most likely for the coming period based on our model.
Source: TradingView, analysis by Yelza
Our model expects Adyen to first rise toward €1,000. After that, we anticipate a pullback to €925. That would mark a new, higher low. As long as the price remains above €843, this recovery scenario remains intact.
From €925, our system expects a strong rally to €1,096, the August high. This may be followed by a correction to €1,000. That level previously acted as resistance and could serve as support after a breakout. From that level, the path is clear to our price target of €1,210—well over 30 percent above the current price.
Conclusion
ASML and Adyen are at opposite ends of the AEX this year, but the same applies to both: their stock prices are not keeping pace with the companies’ performance. ASML is posting record results and expects demand to grow well beyond 2028, while concerns about interest rates and AI investments are weighing on its stock price.
Adyen, on the other hand, is growing faster than expected and, after a tough year, is showing the first signs of bottoming out. According to our algorithm, both stocks offer opportunities in the coming months, though patience is required. If you already hold a position in ASML, you might consider holding onto it and adding to your position in the range between €1,350 and €1,375. If you don’t currently hold a position, that same range offers a favorable entry point toward our price target of €2,350. For Adyen, you may consider holding an existing position toward €1,000 and adding to it around €925. If you don’t have a position, you may consider entering the market around €925 with an eye toward our price target of €1,210.
On Wednesday, October 28, 2026, Adyen will publish its third-quarter earnings report.
ASML will follow on Wednesday, January 27, 2027, with its 2026 annual results.
Disclaimer: Investing involves risks. Our analysts are not financial advisors. Always consult an advisor when making financial decisions. The information and tips provided on this website are based on our analysts’ own insights and experiences. They are therefore intended for educational purposes only.