

On May 21, 2026, we discussed ASM International (ASMI) along with ASML and Besi. At that time, ASMI had just more than met our previous price target. Our model calculated a new price target of €1,050. That target was already reached in June. The stock hit a high of €1,093.
After that, sentiment shifted. Since the June peak, the share price has fallen by more than 30%. On Tuesday evening, ASMI presented its third-quarter results, which were exceptionally strong. Today, we’ll break down the numbers and outline the strategy for the coming months for you as an investor.
For background information, we recommend that you first read the article “ASML, Besi, and ASMi: Update with New Price Targets” from May 21, 2026. You can find the article HERE.
How did the third-quarter results turn out?
ASMI posted the best quarter in its history. Revenue came in at €1,159 million, up 45% from a year earlier. Revenue was at the high end of the company’s own forecast and well above analysts’ expectations of approximately €1.10 billion.
Profitability also remained strong. The gross margin came in at 52%. This represents the portion of revenue remaining after deducting direct production costs. The adjusted operating margin rose from 30.9% to 33.4%. Adjusted net income grew by €109 million to €315 million. This adjusted profit excludes items that are not part of normal business operations. The reported net profit, however, fell from €384 million to €308 million. This is because many of those extraordinary items were included in last year’s figures.
The growth comes primarily from the most advanced chip factories. Chipmakers are investing heavily in 2-nanometer and 3- to 5-nanometer production. The latest generation of 1.4-nanometer technology also made a significant contribution for the first time. The smaller the chip, the more important ASMI’s machines are for applying atom-thin layers. In addition, sales to memory manufacturers rose, particularly for the high-speed memory used in AI chips. Demand from China for machines used in less advanced chips remained high.
2030 Goal in Sight Three Years Ahead of Schedule
The real news was in the outlook. For the fourth quarter, ASMI expects revenue of €1,230 million, with a margin of 5% up or down. For all of 2026, growth will thus amount to approximately 35%. For 2027, the company now anticipates revenue of more than €5.7 billion. In July, that figure was still just over €4.6 billion.
That figure is exactly the target ASMI presented in September 2025 for 2030. According to CEO Hichem M’Saad, demand remains very strong. Due to the demand for AI chips, chipmakers’ factories are operating at nearly full capacity. As a result, they are rapidly expanding their production and need additional machines from ASMI to do so. At the same time, ASMI announced a new program to repurchase up to €300 million in its own shares. In doing so, the company is returning money to shareholders and demonstrating confidence in its stock price.
There are also some concerns. A significant portion of revenue comes from China. New U.S. export restrictions could quickly impact that revenue. In addition, investor expectations are now high. At the end of July, ASMI also reported record figures, yet the stock price still fell by 8%. The projected margin for all of 2026 was slightly lower than analysts had hoped. Such a minor disappointment can therefore already cause significant price swings for this stock. This was also evident in October, when the stock price came under heavy pressure once again.
What is the analysts’ outlook on ASMI’s stock price?
Analysts are predominantly positive. Of the twelve banks that cover the stock, eleven recommend buying and one recommends selling. The average 12-month price target was around €1,180 prior to the earnings report. Recent price targets are higher. HSBC targets €1,230, Barclays €1,300, and UBS €1,325. Bank of America stands out with a price target of €1,457. Following the raised forecast for 2027, it stands to reason that more analysts will raise their price targets.
What is Yelza’s outlook on ASMI’s stock price?
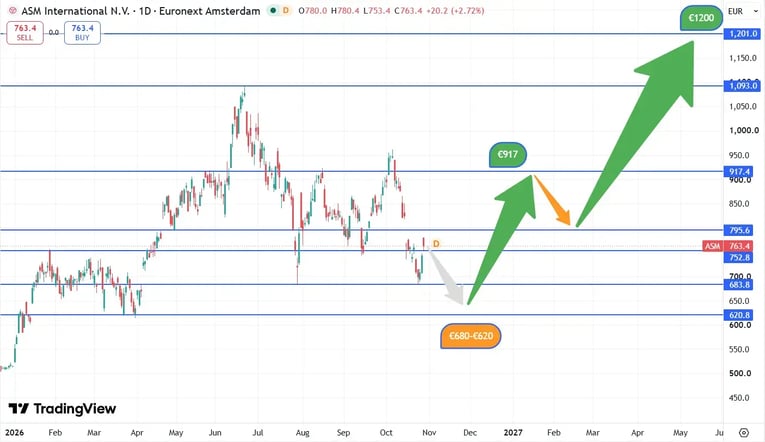
Below you’ll find ASMI’s price chart starting in early 2026. The arrows show the most likely scenario at a glance.
Source: TradingView, analysis by Yelza
According to our model, the most likely scenario is that ASMI will resume its upward trend from its current level around €763. The first move will be a rise to €917. This will be followed by a brief pullback toward €795. That will set the stage for the next upward move toward our 12-month price target of €1,200. From the current price, that represents a rise of over 55%. Our model is thus in line with the consensus among analysts.
Our model does, however, account for the possibility that the price could first pull back once more toward the zone between €680 and €620. That path is indicated in gray on the chart. A pullback to that level does not alter the upward outlook. Only a closing price clearly below €620 would make our scenario less likely. A closing price above €795, on the other hand, would be an initial confirmation that the corrective phase may be largely complete.
In the longer term, our model looks beyond €1,200. For the coming years, we maintain a multi-year price target of €1,600. That represents more than a doubling from the current price. If ASMI manages to meet its significantly raised revenue expectations for 2027, this could lay the groundwork for a further rise toward that level.
Conclusion
ASMI is delivering exactly what investors want to see. Revenue is growing rapidly, margins remain high, and the 2030 target is coming into view three years ahead of schedule. If you already hold the stock in your portfolio, you may want to consider holding onto your position as it heads toward €1,200 and, in the longer term, €1,600. If you don’t yet hold a position, there are two options. The more aggressive investor might consider entering the market now around the current price of approximately €763. Any pullback to the €680 to €620 range could then be used as an opportunity to buy more. The more conservative investor may want to be patient for a while longer and wait to see if that final correction toward the €680 to €620 range materializes.
Disclaimer: Investing involves risks. Our analysts are not financial advisors. Always consult an advisor when making financial decisions. The information and tips provided on this website are based on our analysts’ own insights and experiences. They are therefore intended for educational purposes only.